Your search results

Dubai property market October 2026

Dubai Property Market: October 2026 Sales Rise 5% Monthly, Fall 40% Yearly

Dubai Property Market October 2026: Sales Down 40% on Last Year, Up 5% on September

What 11,898 transactions reveal about the Dubai property market in October 2026 as the year approaches its final stretch.

Key Takeaways

  • Dubai logged 11,898 sales worth AED 34.7 billion in October 2026. Volume rose 5.4% on September and fell 40.1% on last October. Value jumped 18% on the month.
  • Last October was enormous, at close to 20,000 sales. That is why the annual figures look so harsh.
  • Median price came in at AED 1,640 per sqft, down 1.1% on the month and 3.9% on the year. Still about 60% above 2021.
  • Villas went against the trend: 1,356 sales, up 5.5% on last year, and 26% of all the money. Apartments fell 45.2%.
  • Resale took 55% of the value this month. New-build sales took 45%.

QUICK ANSWER:Is the Dubai property market crashing? Not on October’s numbers. Sales are well below last year’s record pace, but they ticked up on September, the value of deals jumped 18%, and the median price is only about 4% lower than a year ago. It looks like a smaller, more selective market that has found a floor around 12,000 sales a month.

Dubai property market October 2026
Dubai Real Estate Market Report

Dubai Property Market: October in Perspective

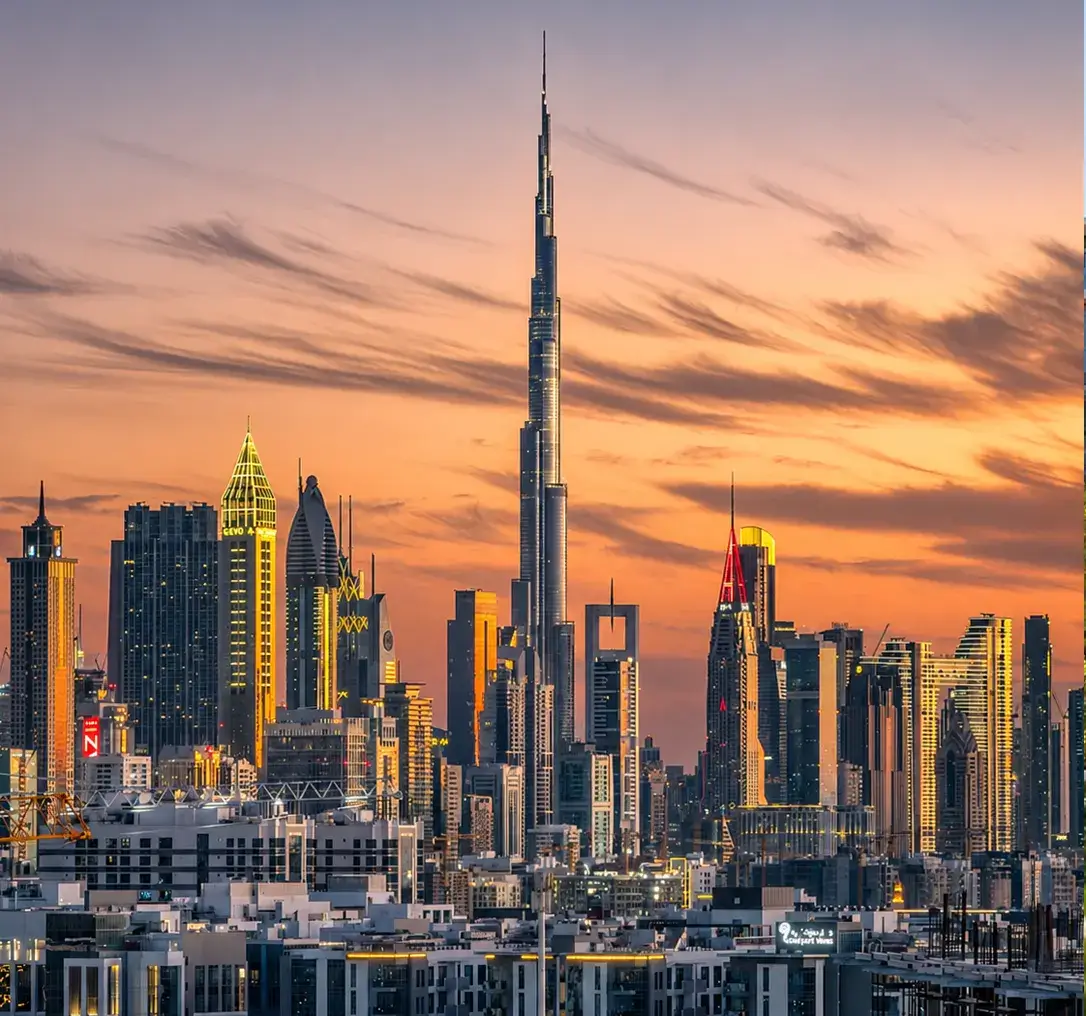
11,898 property sales. AED 34.7 billion in transactions. A 40% annual decline at first glance – but a closer look reveals a more measured market, with villas gaining ground and transaction values moving higher.

Market Review October 2026 Source: DXB Interact
Understanding the Numbers

Read the October headline quickly and it looks bad. Dubai recorded 11,898 property sales, about 40% fewer than the same month last year. Read it properly and the picture is calmer.

September’s number was lower, the total value of deals rose almost a fifth, and villas actually sold more than they did a year ago.

Below is our read of the October figures from DXB Interact, which pulls from Dubai Land Department records. We’ve stuck to what the numbers say and flagged the places where we’re reading between the lines.

October at a Glance

The Numbers Behind the Market

Total Sales Value
AED 34.7B
+18% vs September
Average Deal Size
AED 2.9M
vs AED 2.6M in September
Median Price / Sq Ft
AED 1,640
-1.1% vs September
01

A Small Bounce, Against a Very Big Comparison

Transaction volumes and values

Start with the raw figures. 11,898 sales and AED 34.7 billion in value. Volume was up 5.4% on September. Value was up 18%, so the average deal got noticeably bigger: about AED 2.9 million this month, against roughly AED 2.6 million in September.

The year-on-year hit of 40.1% looks dramatic because October 2025 was a monster. Working back from the report’s percentages, that month was close to 20,000 sales and around AED 59 billion in value. Almost any month would look weak next to it.

The monthly line tells the calmer story. Sales sat near 19,000 in November and December, slid to around 17,000 in January and February, dropped to about 14,000 in March and April, and touched roughly 10,000 in May. After a recovery to 14,000 in June and July, the last three months have read 12,000, 11,000 and 12,000. These are rounded chart labels.

That looks like a market settling at a lower level, not one still falling.
Market Verdict

Volumes are far below last year’s peak, but the last three months have held in a tight 11,000 to 12,000 range. October was a modest bounce, not a breakdown.

02

Prices: Another Small Step Down

Median price per square foot

The median price per square foot came in at AED 1,640, down 1.1% on September and 3.9% on October last year. That is a slightly bigger annual dip than September’s, so it is worth saying plainly: prices are drifting lower, gently.

October Median Price / Sq Ft
AED 1,640
-1.1% Monthly   |   -3.9% Annually

Cavendish Maxwell flagged in early September that August had brought Dubai’s first annual price decline in around five and a half years, as reported by Khaleej Times on 7 September. Two months on, the data still shows a small decline rather than anything sharper.

Put it in proportion. The DXB Interact yearly series for October runs from about AED 1,043 in 2014, to roughly AED 1,028 in 2021, to a peak of around AED 1,703 last year. At 1,640 we are still about 60% above 2021 and only 3 to 4% under the peak.

Market Verdict

A 1% monthly dip and a 4% annual one is a market easing, not capitulating. The thing to watch is whether the next few months keep stepping down at this pace or speed up.

03

Apartments Shrunk. Villas Grew.

Performance by property type

The biggest difference in October was between apartments and villas. Apartments remained the dominant property type, but villas recorded stronger performance.

Property Type Sales vs Sep vs Oct 2025 Sales Value
Apartments 8,888 -2.0% -45.2% AED 15.5B
Villas 1,356 +62.4% +5.5% AED 9.1B
Townhouses 649 +8.0% -48.9% AED 2.0B
Commercial 540 0.0% -21.5% AED 2.3B
Plots 449 +92.7% +16.0% AED 5.9B

Apartments are still three quarters of all sales and 45% of the money, but they fell 45.2% on last year. Villas did the opposite: 1,356 sales, up 62.4% on September and 5.5% on last October, worth AED 9.1 billion, or 26% of the month’s value.

Apartments

8,888

Largest share of transactions, but sales were down 45.2% year-on-year.

Villas

+5.5%

The only major residential segment in this comparison to record annual sales growth.

Plots

+92.7%

The strongest monthly increase, although a small number of large deals can influence the total.

Plots posted the biggest jump (up 92.7% on the month), but at 449 deals worth AED 5.9 billion, a few very large land transactions can swing that number a lot. We wouldn’t build a theory on it.

Townhouses fell almost as hard as apartments, down 48.9% on last year, and commercial slipped 21.5%.

Market Verdict

The weakness is mostly in apartments and townhouses. Villas are holding up, partly because one project did a lot of the lifting (more on that below).

04

New Build Versus Resale: A Messy Month

Median prices per square foot by property type

Comparing primary (new-build) and resale transactions reveals an interesting difference across property types. Apartments look relatively consistent, while villa prices require a closer look.

Property Type Primary AED/Sq Ft vs Oct 2025 Resale AED/Sq Ft vs Oct 2025
Apartment 1,719 -1.7% 1,522 -2.1%
Villa 1,236 -30.2% 1,631 -2.4%
Townhouse 1,615 -7.4% 1,532 +1.8%
Plot 468 -7.3% 917 +35.3%

Apartments look normal. New-build apartments cost about AED 1,719 per sqft, roughly 13% more than resale at AED 1,522, and both are down about 2% on last year.

Villas are where the table needs a warning label. Primary villas show AED 1,236 per sqft, down 30.2%, and well below resale villas at AED 1,631.

Important context – Tilal Binghatti: That does not mean new villas suddenly got 30% cheaper. A single project, Tilal Binghatti, sold 336 villas at a median of about AED 1.5 million. That’s roughly a quarter of all villa sales this month, and it pulls the primary median down hard. It is a mix effect, not a price collapse.

Plots, as usual, are too thin to read. Resale plots at AED 917 (up 35.3%) and primary plots at AED 468 (down 7.3%) are probably telling you which plots happened to trade.

Market Verdict

Don’t quote the 30% villa drop as a price crash. Quote it as what happens when a big affordable launch dominates the month’s sales.

05

What Actually Sold, and Where

Transaction mix, active communities and best-selling projects

By value, resale took 55% of the money and new builds 45%. That flips September, when primary sales had 53%. Resale deals are fewer but bigger, and this month the big tickets went through the resale market.

The busiest areas by sales count were Al Barsha South Fourth, Dubai South, Al Rowaiyah First, Wadi Al Safa 3 and Wadi Al Safa 5. It is a list of mid-market and emerging communities, not the usual postcard names.

Best-selling projects

  • Primary apartments: Binghatti Skyterraces led with 207 sales at a median of AED 1.1 million. Raw District 2 by Imtiaz (176 sales, median AED 747K), Garden Living (160, AED 900K) and Damac Lagoons Lagoon Views 13 A (146, AED 713K) followed, with Binghatti Skyflame 1 fifth on 113.
  • Primary villas: Tilal Binghatti ran away with it at 336 sales and AED 658 million. Greenz by Danube sold 93 (AED 439 million, median AED 4.5 million), then The Greens at Sobha Sanctuary with 43, Damac Islands 2 Antigua 1 with 42 and Dubai Islands with 29 at a median of AED 9.5 million.
  • Resale apartments: Dune Residency led with 38, then Regalia (30), The Mayfair (26) and SLS Dubai (26). Nobody goes above 38, which shows how spread out resale is.
  • Resale villas: Lunaya led with 21 sales and AED 141 million, then Damac Lagoons Nice 1 and Portofino with 16 each. Victory Heights sold 10 at a median of AED 9.5 million.
Market Verdict

Volume is clustered in a handful of launches at entry-level prices. The money, though, increasingly sits in resale and in premium villas.

06

Mortgages: Counts Steady, Value Down

Mortgage activity and resale funding mix

Mortgage transactions came in at 4,604 in October, up 8% on September but 5.6% below last October. That is a change from September, when lending was growing against the trend. Mortgage value was AED 13.2 billion, down 22.1% on the month and 20.4% on the year.

The value drop is bigger than the count drop, so the average loan was smaller (about AED 2.9 million, against roughly AED 4 million in September). Mortgage value can swing with a few large registrations, so we would not read too much into one month.

In the resale market, DXB Interact’s cash versus mortgage split came out at roughly two thirds cash and one third mortgage. Their method strips out refinancing and primary-market registrations so it reflects real money going into resale purchases.

Market Verdict

Cash still carries about two thirds of resale. Lending is no longer the bright spot it looked like in September, so we would call this one neutral.

07

The Top End Still Trades, with One Number to Treat Carefully

Highest-value apartment and villa transactions

The apartment list opens with a line that reads AED 920 million at Marina Pinnacle in Marsa Dubai. We would not treat that as one flat. A figure that size is far above anything else on the list and looks like a bulk or whole-building transfer recorded in the apartment category.

The next four are more typical for ultra-prime: Balqis Residence Beach Villas on Palm Jumeirah at AED 55 million, W Residences Dubai on the Palm at AED 54 million, Orla by Omniyat on the Palm at AED 49 million and One Sankari West Tower in Business Bay at AED 46 million.

On the villa side, the biggest sale of the month was AED 97 million in Eden Hills, followed by Zuha Island at AED 79 million, Signature Villas at AED 78 million, and The Oasis (Lavita) and District One West at AED 70 million and AED 64 million respectively.

Market Verdict

Headline volumes describe the middle of the market. At the top, large cheques are still being written every month. Just don’t quote the AED 920 million figure as a single apartment sale.

08

Rents: Homes Softer, Commercial Stronger

Typical annual rents and year-on-year movement

Property Type Typical Annual Rent vs Oct 2025
Apartment AED 67.8K -5.8%
Townhouse AED 165K -2.9%
Villa AED 214.5K -4.7%
Commercial AED 113.9K +23.3%

Every residential category is lower than a year ago. Apartments show the sharpest fall at 5.8%. Commercial is the outlier, up 23.3%, which makes it the opposite of September’s picture. Commercial figures are volatile from month to month, so we’d watch whether it holds.

Flat-to-softer prices and falling residential rents mean yields get squeezed a little. If you’re buying to let, run the numbers on today’s rents, not last year’s.

Market Verdict

Residential tenants have a bit more leverage than a year ago. Commercial landlords are the ones with momentum.

09

What We’d Take from All This

What October’s market means for different buyers and sellers

Analysts quoted by AGBI in July described a phase of less speculation, fewer launches and more realistic pricing. October’s data is consistent with that. Here’s how we’d think about it by type of buyer:

  • If you’re buying to live: prices are a few percent below last year’s peak and sales are well down, so you have room to negotiate. Resale apartments (down 2.1%) and resale villas (down 2.4%) are both softer, and sellers know buyers have choice.
  • If you’re investing: work from today’s rents. Residential rents are lower on the year, and the best-selling projects are mostly entry-level launches, so check how much supply is heading to the area before you buy.
  • If you’re selling: price against what is selling now, not last year’s asking price. Resale carried 55% of the money this month, so buyers with cash are out there, but they are picky.
Market Verdict

This is a market that rewards homework. That’s good news for serious buyers and harder going for anyone relying on a quick flip.

Looking Beyond the Headline

A Market Finding Its Balance

October’s figures point to a Dubai property market operating at a lower transaction volume than last year’s exceptional peak, but not necessarily one experiencing a broad-based decline.

Higher monthly transaction values, stronger villa activity and relatively modest price adjustments suggest a market that is becoming more selective. The coming months will show whether this stabilisation continues or develops into a more pronounced slowdown.

Dubai property market October 2026

Frequently Asked Questions (FAQ )

On October’s numbers, no. Sales are down 40% year on year, but against one of the busiest Octobers on record, and they rose 5.4% on September. The median price is about 3.9% lower than a year ago. A crash usually means forced selling and steep price cuts. What the data shows is lower volume and slightly softer pricing.

DXB Interact recorded 11,898 transactions worth AED 34.7 billion, based on Dubai Land Department records. That includes direct sales and DIFC transactions, and excludes mortgage registrations and gift transfers. Figures can shift slightly as late registrations are added.

The median came in at AED 1,640 per sqft in October 2026, down 1.1% from September and 3.9% from October 2025.

It depends on your goal and timeline. In October, resale took 55% of the money and new builds 45%, and new-build apartments cost roughly 13% more per sqft than resale ones. We’d rather look at your budget, timeline and exit plan than give a blanket answer.

For homes, yes. Typical rents were down 5.8% for apartments, 4.7% for villas and 2.9% for townhouses compared with October 2025. Commercial rents bucked the trend, up 23.3%.

By transaction count, the top five were Al Barsha South Fourth, Dubai South, Al Rowaiyah First, Wadi Al Safa 3 and Wadi Al Safa 5.

LUXURY PROPERTY INVESTMENT

Thinking about your next move in Dubai?

Tell us your budget and your timeline and the Haus 51 team will show you what is actually selling in the areas you care about, at the prices it is actually selling for.

Let’s Find the Right Property for You

RELATED NEWS